The sticker price is never what a car costs you. Add-on interest, a chattel mortgage fee, insurance and registration charges can add hundreds of thousands of pesos over five years, and most buyers only find out at the dealership.
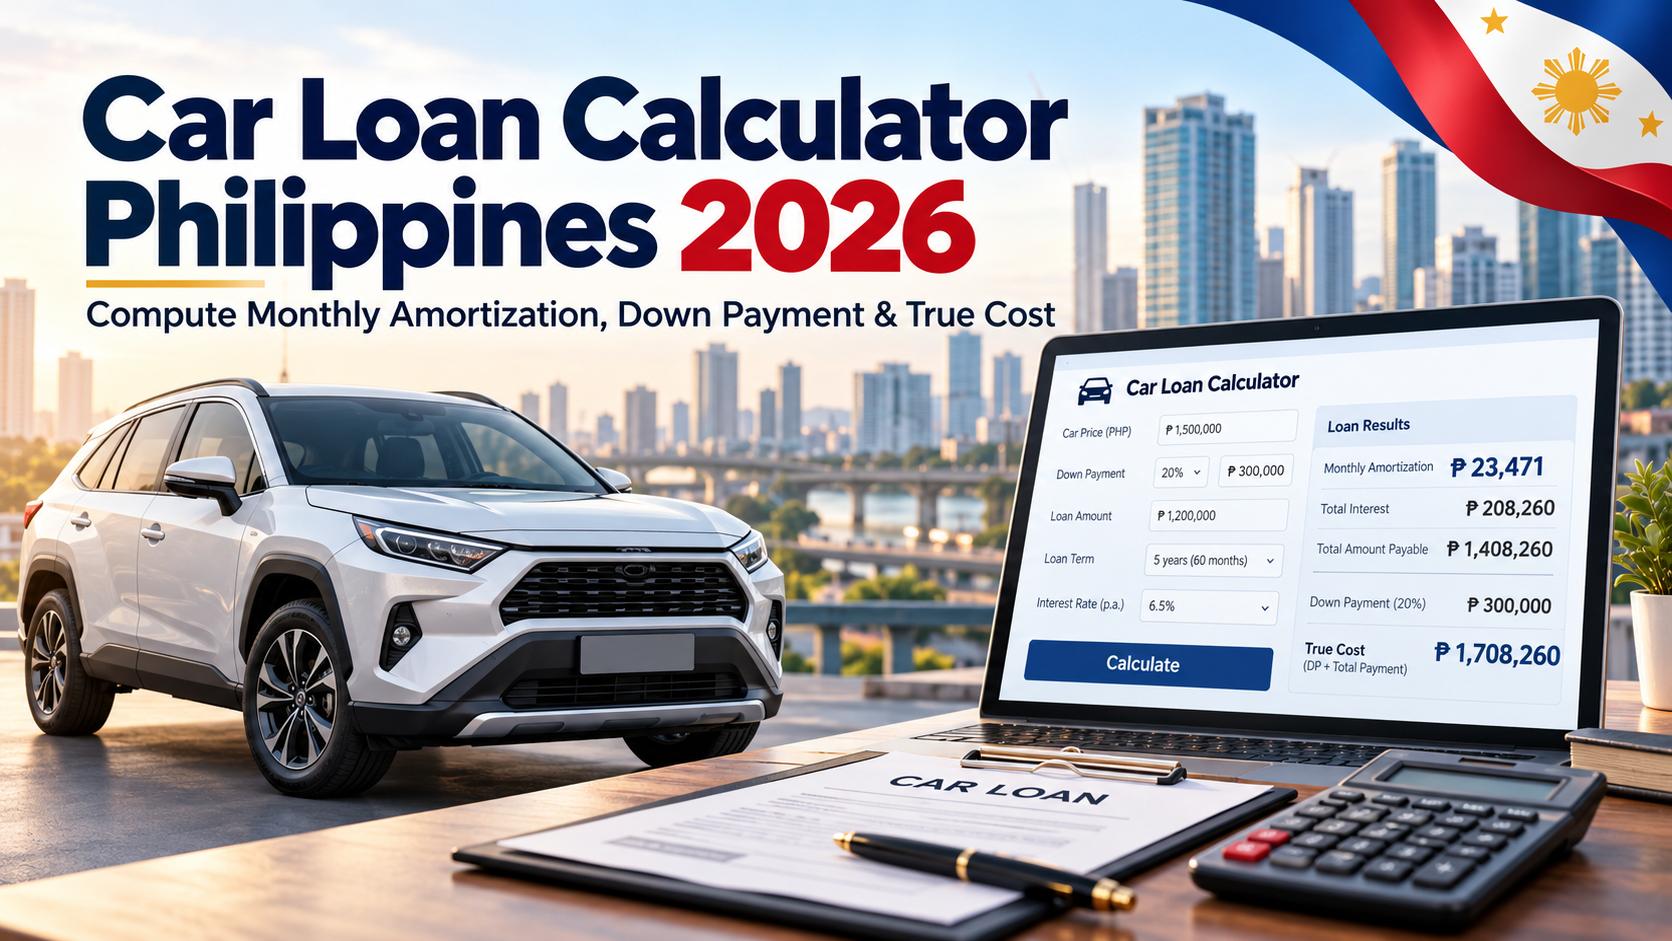
This guide explains how car loans work in the Philippines and how to use our calculator to see the real numbers before you talk to a salesperson. You will see a worked example, learn why a “6.8% rate” is not really 6.8%, and get a checklist of documents to prepare.
Estimates only, not financial advice. Actual approval, rates and fees are set by each lender. Confirm with your bank or dealer.
Use the Car Loan Calculator Philippines
Car Loan Calculator Philippines
Auto Loan Amortization, Down Payment & Bank Requirements (2026)
Typical PH bank add-on rates (BDO, BPI, Metrobank, PSBank) range from 4.5%–6.5%/yr for 36 mos and 6.5%–8.5%/yr for 60 mos. Minimum down payment is usually 20%.
| Period | Payment | Principal | Interest | Remaining Balance |
|---|
Choose a car price (or tap a preset), set your down payment, pick a term from 12 to 84 months and enter the bank’s add-on rate per year. The tool then shows:
- Estimated monthly payment
- Total upfront cash-out (down payment plus fees)
- Principal financed and total interest
- Total cost of the car
- The monthly income a bank may expect, using a 35% rule of thumb
- A year-by-year or month-by-month repayment table
How Car Loans Work in the Philippines
Most Philippine banks and dealer-tied financing arms (such as Toyota Financial Services) lend against the car itself. You pay a down payment, the lender finances the rest, and the car is registered with the lender’s lien on it until you finish paying. That lien is the chattel mortgage.
Two features make Philippine auto loans different from many other countries:
- Add-on interest. Many banks charge interest once on the original loan, not on the shrinking balance.
- Required insurance. Lenders typically require comprehensive insurance for the life of the loan.
Add-On Rate vs. Effective Interest Rate
This is the single most important concept in the whole article.
An add-on rate is charged on the full original loan for the entire term. Monthly payment = (loan + loan × rate × years) ÷ months. Because you are repaying principal every month but interest is still computed on the full amount, the true yearly cost, called the effective interest rate (EIR), is much higher than the headline number.
A useful rule of thumb: the effective rate on an add-on car loan is often around 1.7 to 1.9 times the per-year add-on rate. In published examples, Metrobank’s 5.19% add-on rate equates to roughly 9.4% effective, and BPI’s 31.01% whole-term add-on rate over 60 months works out to about 11.2% effective.
Watch the way banks quote it. Some rate sheets show the add-on for the whole term (for example 30.26% over 60 months), while others show a per-year figure. BDO quotes a yearly rate on the declining balance instead. Our calculator asks for the per-year add-on rate, so convert a whole-term figure by dividing it by the number of years.
| Published whole-term add-on | Term | Per-year figure to enter |
|---|---|---|
| Metrobank 16.90% | 36 months | about 5.63% |
| Metrobank 30.26% | 60 months | about 6.05% |
| BPI 17.76% | 36 months | about 5.92% |
| BPI 31.01% | 60 months | about 6.20% |
Rates are from 2026 published rate sheets and change often. Check the lender’s current sheet, and ask whether the rate is add-on or effective.
How the Calculator Works: The Formulas
No black box. Here is exactly what the tool does:
- Loan amount = car price − down payment
- Total interest = loan × add-on rate × years
- Monthly payment = (loan + total interest) ÷ number of months
- Chattel mortgage fee (estimate) = about 2% of the loan
- Comprehensive insurance (estimate) = about 2.5% of the car price
- LTO registration (estimate) = a flat ₱3,000
- Required monthly income = monthly payment ÷ 0.35
The fee estimates are deliberately rough. Real chattel fees are often quoted at 2% to 3% of the loan, and insurance premiums vary by car, insurer and coverage.
Worked Example: A ₱1,050,000 Car, 20% Down, 60 Months
Using the calculator’s default setup (6.8% per-year add-on):
| Item | Amount |
|---|---|
| Car price | ₱1,050,000 |
| Down payment (20%) | ₱210,000 |
| Loan amount | ₱840,000 |
| Total interest (6.8% × 5 years) | ₱285,600 |
| Total repayment | ₱1,125,600 |
| Monthly payment | ₱18,760 |
| Estimated fees (chattel + insurance + LTO) | ₱46,050 |
| Upfront cash-out | ₱256,050 |
| Total cost of the car | ₱1,381,650 |
| Suggested minimum monthly income | ₱53,600 |
So a ₱1.05 million car costs about ₱331,650 more than its sticker price once interest and fees are included. That gap is exactly what the calculator exists to reveal.
Shorter vs. Longer Terms: Which Costs Less?
A longer term lowers your monthly payment but raises total interest. Here is the same ₱840,000 loan using published 2026 BPI-style rates converted to per-year add-on:
| Term | Per-year add-on | Monthly payment | Total interest | Income needed (35% rule) |
|---|---|---|---|---|
| 36 months | 5.92% | about ₱27,477 | ₱149,184 | about ₱78,500 |
| 60 months | 6.20% | about ₱18,340 | ₱260,400 | about ₱52,400 |
The 60-month plan saves roughly ₱9,100 every month but costs about ₱111,000 more in interest. If your budget can handle the 36-month payment, you keep that money. If not, a longer term may be the difference between getting approved and being declined.
How Much Down Payment Do You Need?
Published 2026 bank terms show a range:
- Brand-new cars: commonly 15% to 20%. BPI lists as low as 15%, and BDO asks 20% for personal use.
- Second-hand cars: usually 30% or more. Several large banks ask for at least 30%, and some business-use loans ask 40%.
- Dealer promos: low or even zero down payment offers exist, but they often come with higher rates or shorter terms.
A bigger down payment shrinks your loan, your interest and the income you need to qualify. Try moving the slider in the calculator from 15% to 30% and compare the total cost.
The Costs the Sticker Price Hides
When you budget, set aside money for:
- Chattel mortgage fee: often 2% to 3% of the loan
- Comprehensive insurance: required for the loan period and renewed every year
- LTO encumbrance and registration: a few hundred pesos for the encumbrance plus registration costs
- Documentary stamp tax and notarial charges
- Late charges: some banks publish steep monthly penalties on unpaid dues
These rarely appear in an advertised monthly payment, so treat the “Total Upfront Cashout” figure in the calculator as the number to save for.
What Income Do Banks Expect?
Lenders look at whether your monthly amortization fits your income. Our tool uses a 35% ceiling as a planning rule, but each bank has its own policy. Published examples include a gross family income of ₱50,000 a month for BDO and ₱40,000 for EastWest on used-car loans. Treat these as moving targets and verify directly.
Documents to Prepare for a Car Loan Application
Requirements differ by lender, but you can usually expect to prepare:
- A completed, signed application form
- At least one valid government-issued ID (a passport is often preferred)
- Proof of income: certificate of employment and payslips, or an ITR and bank statements if self-employed
- Proof of billing or address
- Co-borrower documents, if applicable
A few practical notes on getting these documents in order:
- Check the accepted valid IDs for government and police transactions so your ID and name spelling stay consistent across applications.
- If you need a document to prove where you live, see the barangay certificate requirements for 2026.
- Some lenders and institutions ask for background documents during financial transactions. This overview of when a police clearance is needed for loans and financial transactions explains the situation, and the police clearance requirements guide walks you through preparing one.
- If a lender or employer asks for an NBI document instead, read the NBI clearance guide first.
Buying a Second-Hand Car? Add These Steps
Used-car loans are stricter and costlier. BPI’s 60-month second-hand add-on rate is far higher than its brand-new rate (44.32% versus 31.01%), and banks cap the loan at a smaller share of the car’s value. Some also limit vehicle age, for example a model no older than six years at the time the loan matures.
Before you pay for a used vehicle:
- Confirm the seller’s ownership papers match the car.
- Verify the vehicle through the PNP HPG clearance process, which is commonly used to check motor vehicles during transfers.
- Run the numbers in the calculator using the used-car rate, not the new-car rate.
7 Ways to Lower What You Pay
- Put down more than the minimum.
- Choose the shortest term your monthly budget can handle.
- Compare at least three banks plus the dealer’s in-house financing.
- Ask for the effective interest rate, not just the add-on rate.
- Compare insurance quotes where the lender allows it.
- Ask whether early settlement is allowed and what the penalty is.
- Keep a buffer so you never trigger late charges.
Frequently Asked Questions
Final Thoughts
A car loan is a five-year commitment, so spend ten minutes on the numbers before you sign anything. Run two or three scenarios in the calculator, compare effective rates, and prepare your documents early. If you are buying used, add the verification steps above.
Sources checked: published 2026 rate and requirement pages for BPI, BDO and Metrobank car loans, and 2026 comparison guides on add-on versus effective rates. Rates and fees change frequently, so always confirm with the lender.